Shows
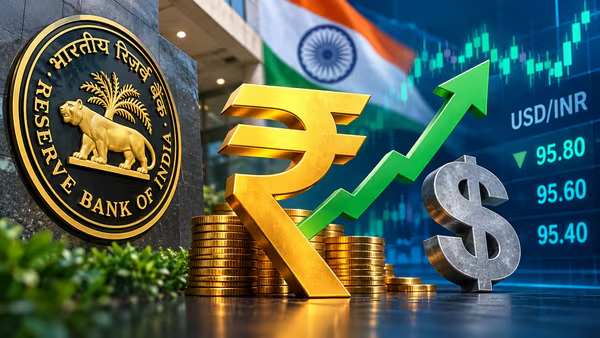
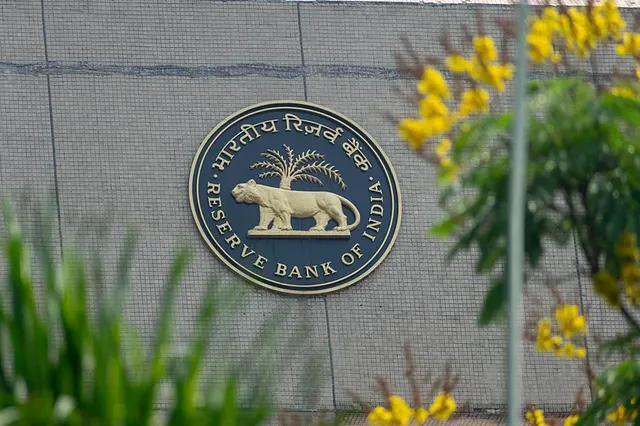
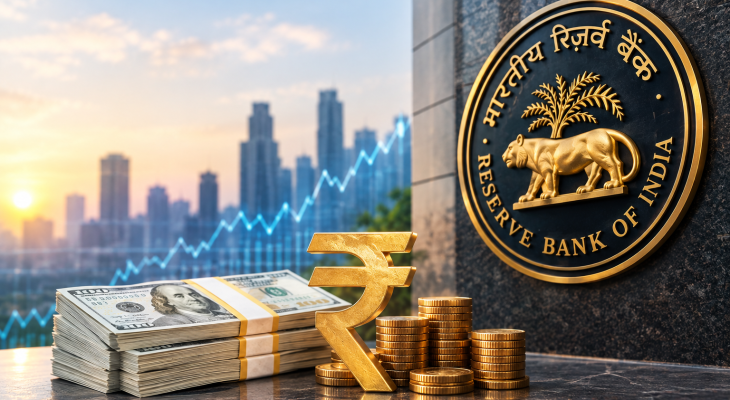
The Reserve Bank of India (RBI) has announced a key measure to ease pressure on the rupee in the foreign exchange market. From October 12, the central bank will directly meet the daily dollar requirements of three major public sector oil marketing companies Indian Oil Corporation, Bharat Petroleum and Hindustan Petroleum. The move follows the rupee’s fall to a record low of ₹96.74 against the US dollar last Friday.
India relies heavily on crude oil imports to meet its energy needs. According to August data, the country imports around 23 million tonnes of crude oil every month, worth approximately $11.7 billion, or about $377 million a day. The three state owned oil companies account for nearly 55% of these imports. They generally purchase dollars in the spot market to pay for crude oil imports. Based on August figures, their daily foreign exchange requirement is estimated at around $200 million. Although payments for Russian crude are also made in UAE dirhams or Indian rupees, the companies still need at least $114 million a day for payments made directly in dollars.
Under the special window introduced by the RBI, these companies will no longer need to compete in the spot market to meet their dollar requirements. Instead, the central bank will sell dollars directly to them at prevailing market rates through designated banks. The arrangement is expected to reduce daily dollar demand in the open market, ease volatility in the foreign exchange market and help limit further pressure on the rupee, according to banking experts.
Comments (0)
No comments yet
Be the first to comment!